


How Much Income Do You Need to Buy a House on Long Island? The Numbers That Matter and the ones that don't.
Updated: 1 day ago
Want to watch instead?
Lets be honest about what you are going to read for a second:
I know what you are hoping for in this article and it’s not “well it all depends” but unfortunately thats the truest answer. Because I want to leave you with something tangible I am going to give you real world examples to compare and contextualize, to do that, Ive asked five local Long Island trusted lenders what the average homebuyer income is currently for transactions coming across their desks, and what is the lowest income they have seen qualify for a home on Long Island. (Look at me working for you, and you haven’t even met me yet!) BEFORE we get there, we need to chat, so pull up a chair.
This is one of the first questions buyers ask, and it makes sense.
You want a number. "Do I need to make $100,000? $150,000? $250,000 to buy a home on long island?"
The truth is, there isn't a magic salary that unlocks homeownership.
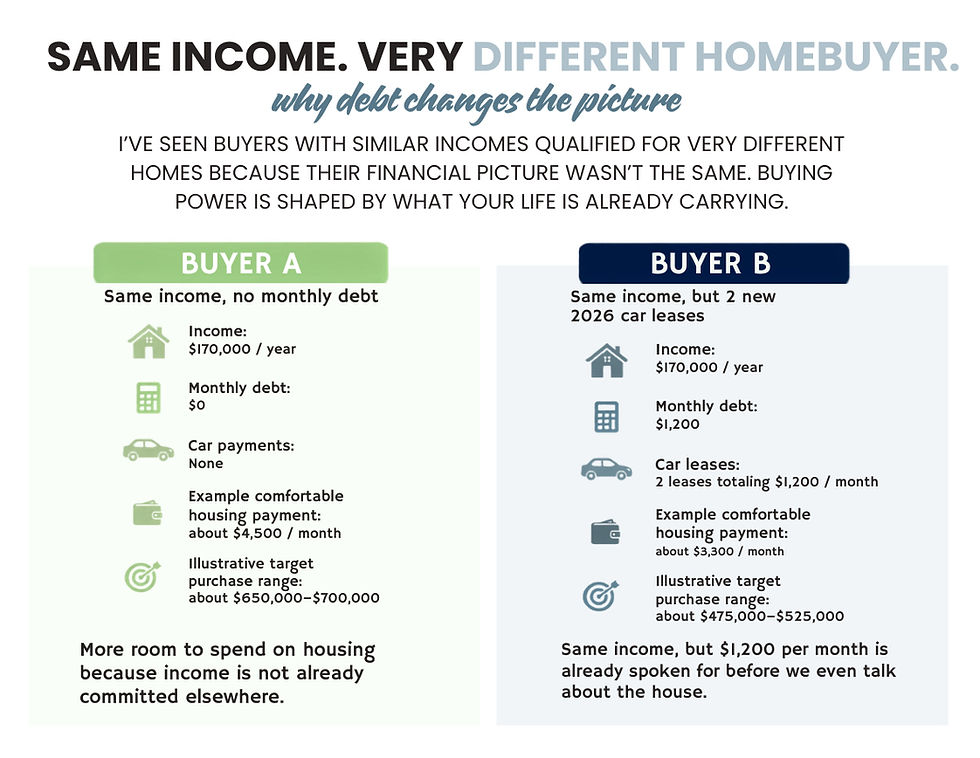
I've seen buyers with similar incomes qualify for very different homes because their financial picture wasn't the same. A buyer who makes 170K may have no debt and qualify for more, and another may have 2 new 2026 car leases, leaving them to qualify for a lot less. Buying a home isn't about reaching a salary milestone. It's about understanding what creates a payment that fits comfortably into your life.
Finding this useful so far and just want a personal solution? Let's chat, click me!
Sorry for the shameless plug, back into it... so first, I want to be clear, you are kinda asking the wrong question. This is how you should look at your salary (if you want to be a savvy homebuyer):
Start with your take home pay amount-
Subtract your monthly Debts (monthly minimum credit card payments, loans, car payments insurance, etc)-
You are left with this Extra Number-
(We start working with that Extra zone, one of the first things we do is plan how much you are comfortable spending inside of that zone and then we work backwards to a desired purchase amount.)
Your pre-approval and your purchase amount are not always the same because when you do this the smart way, we know EXACTLY what life looks like after purchase, and what you want to spend.
Here are some examples:

Why Salary Isn't the Whole Story
Lenders don't look only at your paycheck.
They also consider:
Existing monthly debt
Student loans
Car payments
Credit cards
Down payment
Credit score
Interest rate
Property taxes
Homeowners insurance
Someone earning $125,000 with very little debt may have more flexibility than someone earning $125,000 who carries significant monthly obligations. Income opens up options but is only one part of the story.

Property Taxes Can Change the Equation
This is where Long Island becomes different from many other markets.
Two homes listed at the same price can have monthly payments that differ by hundreds of dollars because of property taxes. That's why I encourage buyers to compare the total monthly payment, not just the purchase price. A home that's slightly more expensive with lower taxes may fit your budget better than a cheaper home with significantly higher taxes. Looking only at price can lead you to the wrong conclusion, and I have seen it happen over and over again.
What Pre-Approval Actually Tells You
Many buyers assume a pre-approval sets their budget.
It doesn't. It tells you what a lender is willing to finance based on today's information. THATS IT. That number isn't set in stone, it's simply a data point. *ONE data point at that... (different lenders can approve you for different amounts but thats a story for another time...)
Your ideal budget should reflect your lifestyle, future goals, and comfort level, not just the maximum amount a lender approves.
What I Tell My Own Clients
One of the biggest mindset shifts I see is this: People stop asking,
"How much do I have to make to buy a home on Long Island?”
And they start digging deeper,
“What monthly payment corresponds with what purchase price,
am I ready to spend that monthly, and also be comfortable?”
That's a much better question.
NOW WE ARE COOKING W GASSSSS.
I would rather help someone buy a home that leaves room for investing, vacations, unexpected repairs, and peace of mind than encourage them to spend every dollar they're approved to borrow. Shocking.
Real estate should strengthen your financial position over time, not become the reason your finances feel tight.
Im always around to help,
Xo Ash.
631-824-4288


Comments